

納税フォーム
Form 6781 は、税金に関する情報を関連する税務当局に報告するために使用される文書である納税申告書の 1 つです。納税者の状況や場所によって、連邦税、州税、地方税など、さまざまな種類の納税申告書があります。
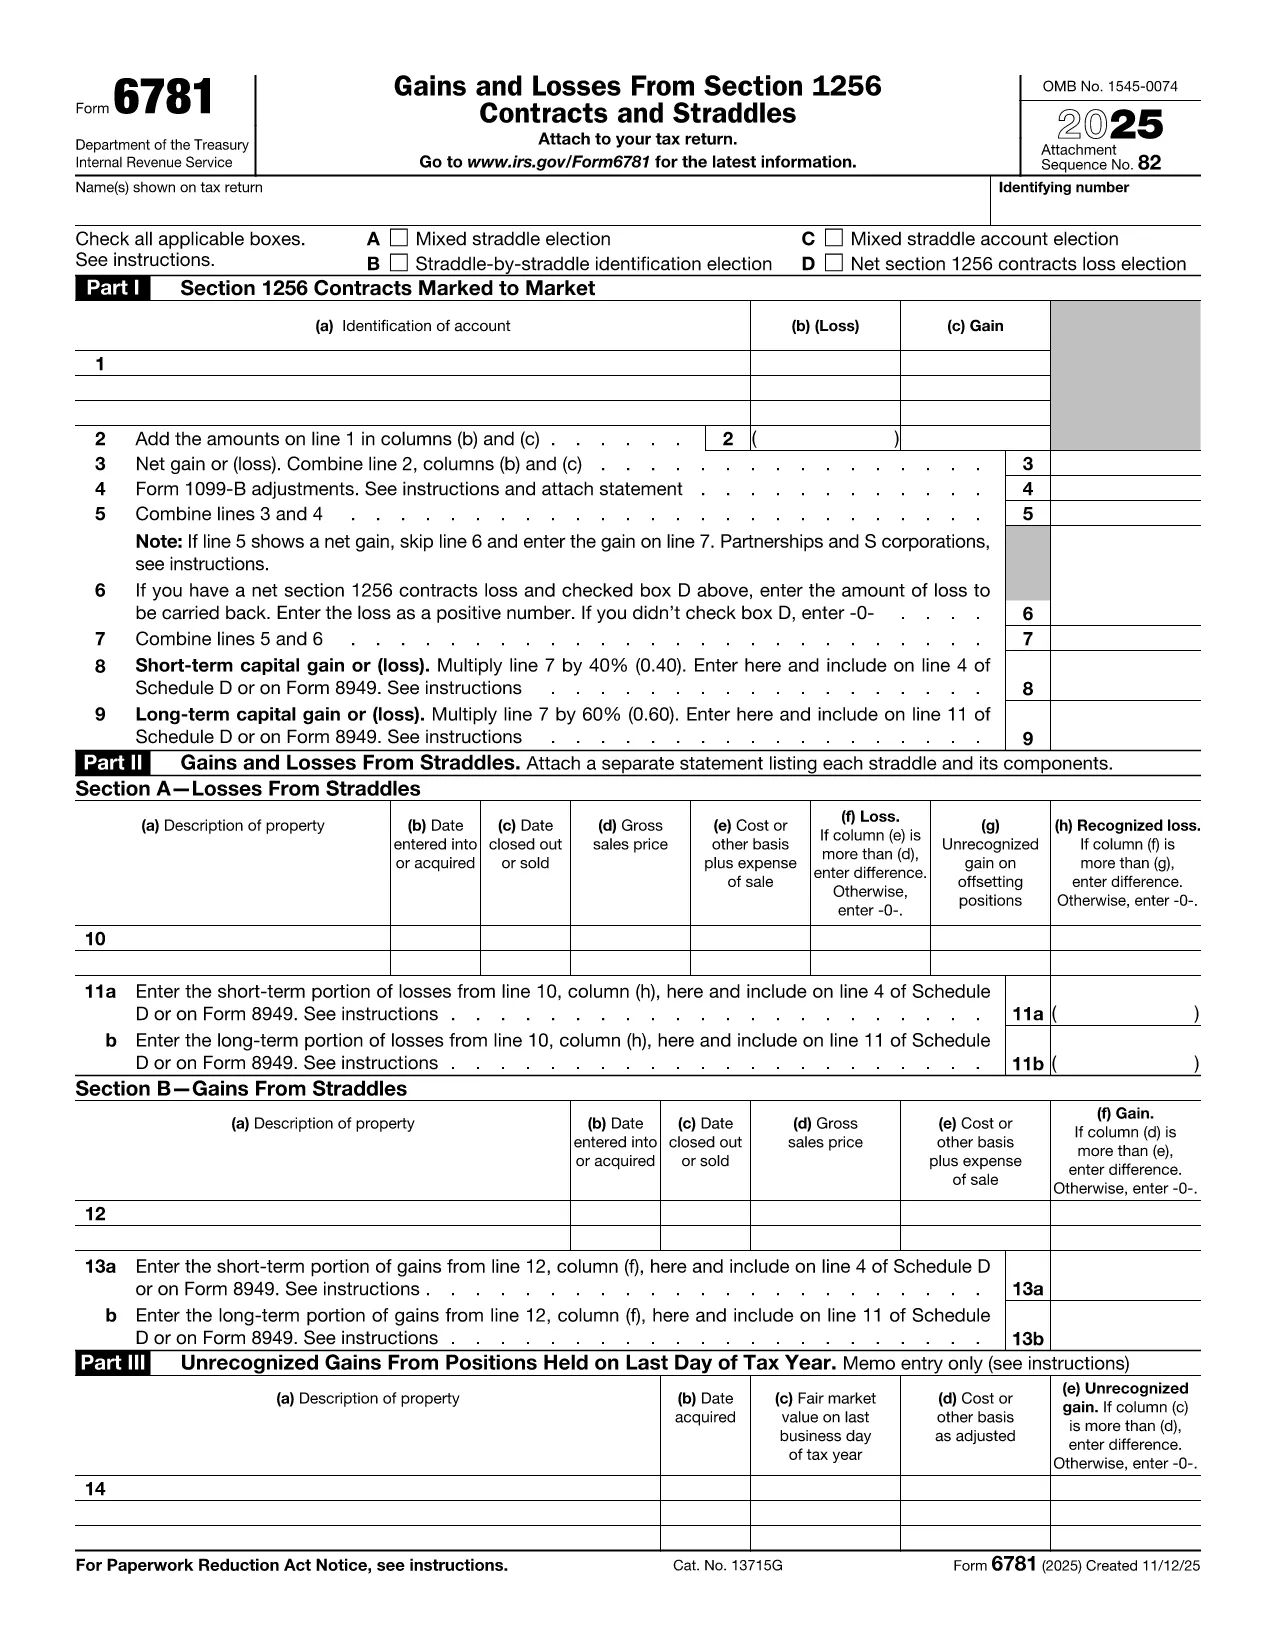
Form 6781, officially titled Gains and Losses From Section 1256 Contracts and Straddles, is required for traders, investors, and any taxpayer who holds regulated futures, options, foreign‑currency contracts, or other Section 1256 instruments. This one‑page form reports both short‑term and long‑term capital results, and it includes election boxes for mixed‑straddle and loss‑carryback options.
The form captures three distinct sections:
Each part helps the IRS calculate the correct mix of short‑term (40%) and long‑term (60%) capital treatment, regardless of the actual holding period.
Instead of printing, scanning, or editing the PDF in a desktop editor, you can complete the form directly in your browser:
The online filler validates numeric fields and ensures required boxes are checked, reducing the chance of IRS rejections.
Form 6781 is attached to your individual, corporate, partnership, or trust tax return (Form 1040, 1120, 1065, or 1041). The filing deadline matches the underlying return – typically April 15 for individuals, with extensions available.
If you traded any Section 1256 contracts during the tax year, you must file Form 6781, even if the net result is a zero gain or loss.
Ready to get started? Click the button below to open the fillable version and complete it in seconds.
Section 1256 contracts include regulated futures, foreign‑currency contracts, non‑equity options, dealer equity options, and dealer securities futures contracts.
Yes. If you held any Section 1256 contracts during the year, you must file Form 6781 even if the net result is zero.
Form 6781 is attached to the main tax return (Form 1040, 1120, etc.). When you e‑file the return, the completed PDF is included automatically.
The deadline matches the filing deadline of the associated tax return – typically April 15 for individuals, with extensions available.
Regardless of how long you held the contract, 60% of the gain or loss is treated as long‑term capital, and 40% as short‑term capital.
Yes, individuals may carry back a net Section 1256 loss up to three prior years, but corporations, partnerships, estates, and trusts are not eligible.
Common mistakes include forgetting to check required election boxes, double‑reporting contracts in both Part I and Part II, and mis‑calculating the 60/40 split.
The fillable PDF can be downloaded, printed, and mailed, but using the online filler reduces errors and speeds up the process.
Form 6781 は、税金に関する情報を関連する税務当局に報告するために使用される文書である納税申告書の 1 つです。納税者の状況や場所によって、連邦税、州税、地方税など、さまざまな種類の納税申告書があります。
オンラインで PDF フォームに記入する最も簡単な方法
フィルセッションを削除
編集セッションを削除する