

税务表格
Form 6781 是一种税表,是用于向相关税务机关报告与税收相关的信息的文件。有多种类型的税表,包括联邦、州和地方税表,它们可能因纳税人的情况和地点而异。
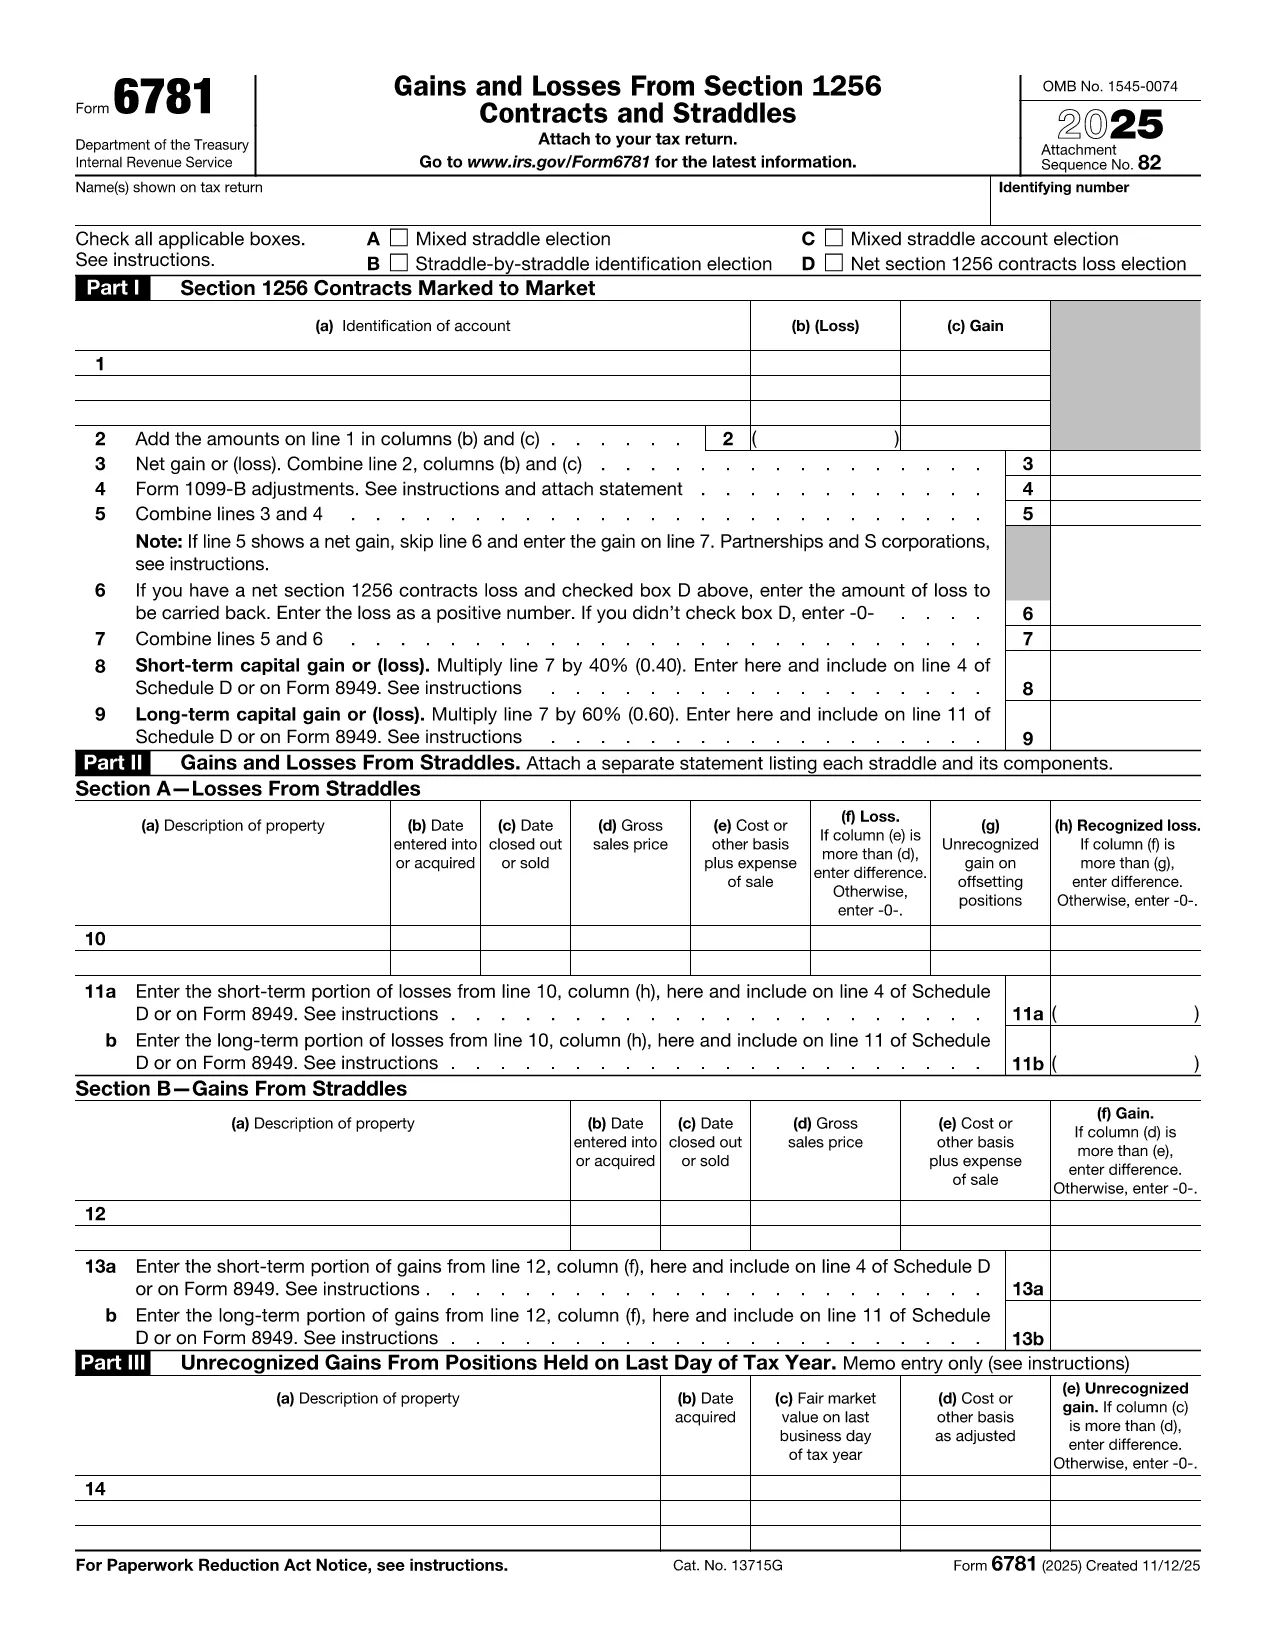
Form 6781, officially titled Gains and Losses From Section 1256 Contracts and Straddles, is required for traders, investors, and any taxpayer who holds regulated futures, options, foreign‑currency contracts, or other Section 1256 instruments. This one‑page form reports both short‑term and long‑term capital results, and it includes election boxes for mixed‑straddle and loss‑carryback options.
The form captures three distinct sections:
Each part helps the IRS calculate the correct mix of short‑term (40%) and long‑term (60%) capital treatment, regardless of the actual holding period.
Instead of printing, scanning, or editing the PDF in a desktop editor, you can complete the form directly in your browser:
The online filler validates numeric fields and ensures required boxes are checked, reducing the chance of IRS rejections.
Form 6781 is attached to your individual, corporate, partnership, or trust tax return (Form 1040, 1120, 1065, or 1041). The filing deadline matches the underlying return – typically April 15 for individuals, with extensions available.
If you traded any Section 1256 contracts during the tax year, you must file Form 6781, even if the net result is a zero gain or loss.
Ready to get started? Click the button below to open the fillable version and complete it in seconds.
Section 1256 contracts include regulated futures, foreign‑currency contracts, non‑equity options, dealer equity options, and dealer securities futures contracts.
Yes. If you held any Section 1256 contracts during the year, you must file Form 6781 even if the net result is zero.
Form 6781 is attached to the main tax return (Form 1040, 1120, etc.). When you e‑file the return, the completed PDF is included automatically.
The deadline matches the filing deadline of the associated tax return – typically April 15 for individuals, with extensions available.
Regardless of how long you held the contract, 60% of the gain or loss is treated as long‑term capital, and 40% as short‑term capital.
Yes, individuals may carry back a net Section 1256 loss up to three prior years, but corporations, partnerships, estates, and trusts are not eligible.
Common mistakes include forgetting to check required election boxes, double‑reporting contracts in both Part I and Part II, and mis‑calculating the 60/40 split.
The fillable PDF can be downloaded, printed, and mailed, but using the online filler reduces errors and speeds up the process.
在线填写 PDF 表单的最简单方法
删除填充会话
删除编辑会话